
Holiday let EPC rules in England and Wales
Holiday lets are excluded from higher private rental energy standards for now. Certificate requirements are a separate question.
Read more about Holiday let EPC rules in England and WalesThe Furnished Holiday Lettings tax regime ended in April 2025. Holiday accommodation can still be let, but qualifying for the old FHL rules no longer gives an ongoing property business its former tax treatment.
For Bristol owners considering multi platform hosting, explore our short let management in Bristol.
The immediate job is to check the first return under the new rules and make sure the next year’s forecast uses the right costs. An owner with a mortgage, a company owner and someone selling a former holiday let can have very different tax positions.
Reviewed on 14 October 2026. This is general UK tax information, not advice on your circumstances. Ask a qualified tax adviser to check a return, disposal or change of ownership.
For individuals, the change applies from 6 April 2025 for Income Tax and Capital Gains Tax. For companies, the general commencement date is 1 April 2025 for Corporation Tax and tax on chargeable gains. Company accounting periods and capital allowance rules need checking separately. HMRC explains the commencement rules.
The 2024/25 individual tax year was the final year in which a property could qualify under the FHL regime. The 2025/26 return is the first individual return under the replacement property income rules. The current 2026/27 tax year also uses those rules. Do not reuse a historic FHL calculation for either year.
On 28 October 2026, the Budget proposed property Income Tax rates of 24%, 44% and 49% from 6 April 2027 for England, Wales and Northern Ireland. These are to be legislated for in Finance Bill 2026 to 2027. They do not change the rates for the 2025/26 return or the current 2026/27 year. Our Budget property tax update explains the distinction and a limited forecast example.
The separate Visitor Levy (England) Bill was introduced on 4 November 2026. Our England visitor levy Bill update explains the proposed local powers, the longer stay distinction and what Bristol hosts can prepare. It creates no new charge on current bookings.
Individual residential landlords generally receive a basic rate tax reduction for qualifying finance costs, rather than deducting those costs from rental income. Companies are not subject to that individual finance cost restriction. HMRC’s FHL clarification makes this distinction.
For 2026/27, the reduction is normally 20% of the lowest of qualifying finance costs, property business profits and adjusted total income above the personal allowance. It cannot create a refund. Unused qualifying finance costs may carry forward. This is not a guaranteed 20% refund of every mortgage payment. Mortgage capital repayments are not interest. HMRC explains the calculation.
Assume an individual in England receives £30,000 rent, pays £8,000 allowable operating expenses and £10,000 qualifying mortgage interest. Assume all £22,000 taxable property profit falls in the 40% band, the full £2,000 finance cost reduction is available, and no other relief, loss or allowance adjustment applies.
The property tax is £8,800 less £2,000, giving £6,800. Cash before tax is £12,000. Cash after this tax is £5,200, before mortgage capital repayments and capital spending. Taxable profit, cash left in the bank and gross booking income are different figures. This example is not a personal tax estimate.
New furniture, fixtures and furnishings no longer qualify for the special FHL capital allowance treatment. However, qualifying expenditure already in an existing capital allowance pool can continue to receive the relevant allowances under transitional rules. Keep the pool schedule and its supporting invoices rather than writing the balance off. HMRC’s capital allowance guidance links to the detailed transition.
Replacement of domestic items relief may apply to eligible replacement expenditure under the ordinary property rules. It is not a general deduction for buying the initial furnishings, and improvements need their own treatment. Repair invoices and capital improvements should not be grouped together simply because they were paid during the same refurbishment.
Carried forward FHL losses also need transferring correctly. An individual’s former UK FHL losses can be used against the ongoing UK property business; former overseas FHL losses follow the overseas property business. Company losses follow the Corporation Tax rules. They do not all become a deduction against an individual’s salary. HMRC explains how FHL losses continue after repeal.
For an individual selling residential property in 2026/27, the usual Capital Gains Tax rates are 18% within the available basic rate band and 24% above it. The rate applies to the taxable gain, not the whole sale price. Companies calculate chargeable gains under Corporation Tax instead. Check the current HMRC rates.
Business Asset Disposal Relief is not automatically available because a property used to qualify as an FHL. The special treatment ended for an ongoing FHL business from April 2025. There are limited transitional cases, including where an eligible business actually ceased before 6 April 2025 and qualifying assets are disposed of within the normal three year window. Abolition itself did not count as cessation. HMRC sets out the relief and contract rules.
Where a disposal genuinely qualifies for Business Asset Disposal Relief, the rate was 14% for disposals from 6 April 2025 to 5 April 2026 and is 18% from 6 April 2026. The historic 10% rate is not the current rate. Check eligibility and the applicable disposal date with your adviser before relying on any relief.
Booking platforms covered by the UK reporting rules collect seller information and report annually to HMRC. Calendar year 2026 information is due by 31 January 2027. That is the platform’s reporting cycle, not a replacement for your own tax calculation.
Platform summaries can use the calendar year, whereas an individual’s tax year runs from 6 April to 5 April. They can also show amounts after platform deductions. Reconcile the reported figures with gross booking receipts, refunds, commission, direct bookings and expenses for the correct period. Do not assume a bank payout is the gross rent, or that a platform has reported every source of income. HMRC explains what platform reports contain.
The normal online filing and payment deadline for the 2025/26 individual Self Assessment return is 31 January 2027. The paper return deadline is 31 October 2026. If you first needed to tell HMRC about a filing requirement for that year, the usual 5 October 2026 notification date has passed. Contact HMRC promptly if you missed it rather than waiting until January.
Payments on account can create an additional cash requirement and a July payment date. Company filing and payment dates follow a different timetable. Check the official Self Assessment deadlines against your circumstances.
Making Tax Digital is a separate obligation. Subject to eligibility and exemptions, individuals with qualifying income over £50,000 in 2024/25 should have started using it from 6 April 2026. The threshold is over £30,000 in 2025/26 for a start from 6 April 2027. This is qualifying income, not profit after expenses. Use HMRC’s eligibility guidance rather than assuming an annual platform summary is sufficient. Those already using MTD can check the reporting period and records in our 7 November 2026 update guide.
Removing the FHL regime does not answer that question. Compare realistic income after commission, cleaning, utilities, insurance, maintenance, management, voids and finance costs. Then have the tax calculated for the actual owner. A higher nightly rate is not evidence of a better annual return.
Include the cost and practical consequences of changing use. Mortgage conditions, insurance, planning, leases and the tenancy rules can all affect what is possible. A company transfer is not a simple workaround for the finance cost restriction; it needs a separate review of transfer taxes, gains, borrowing and ongoing costs.
We can help compare the operating forecasts for short stays and long term management and organise the property’s income and expense records for your accountant. Ask us to review your property’s letting options. For Bristol owners, our short let management in Bristol service covers day to day operations. The tax decision should follow a forecast you can explain, not an old relief or an optimistic headline income.
We handle pricing, guest communication, cleaning, maintenance and owner reporting.
Holiday lets are excluded from higher private rental energy standards for now. Certificate requirements are a separate question.
Read more about Holiday let EPC rules in England and Wales
At The Upgrade Authority, we are committed to providing our property owners and guests with the best possible experiences. To further...
Read more about The Upgrade Authority Announces Partnership with Pikl Insurance Services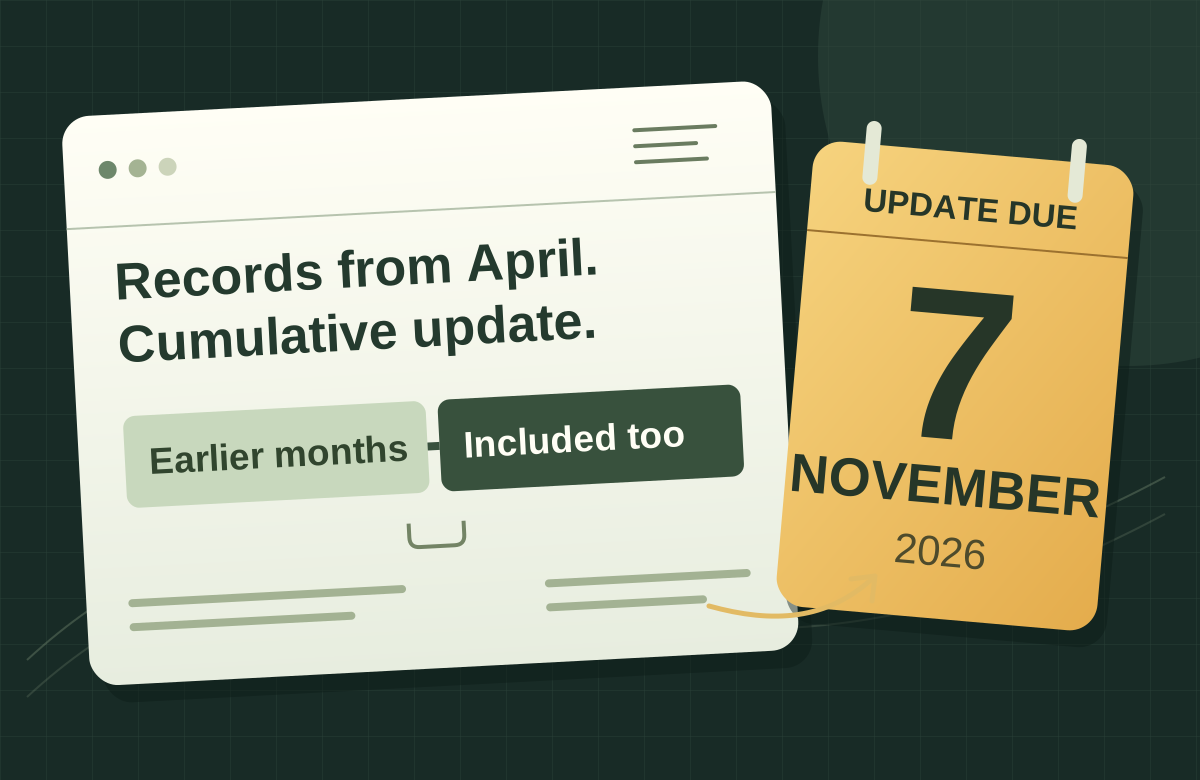
Which landlords need the 7 November 2026 MTD update, the cumulative period it covers and how to prepare useful records with an accountant or agent.
Read more about Making Tax Digital: what landlords need for the 7 November update